Find the best way to finance your dream home
Start with your payment capacity
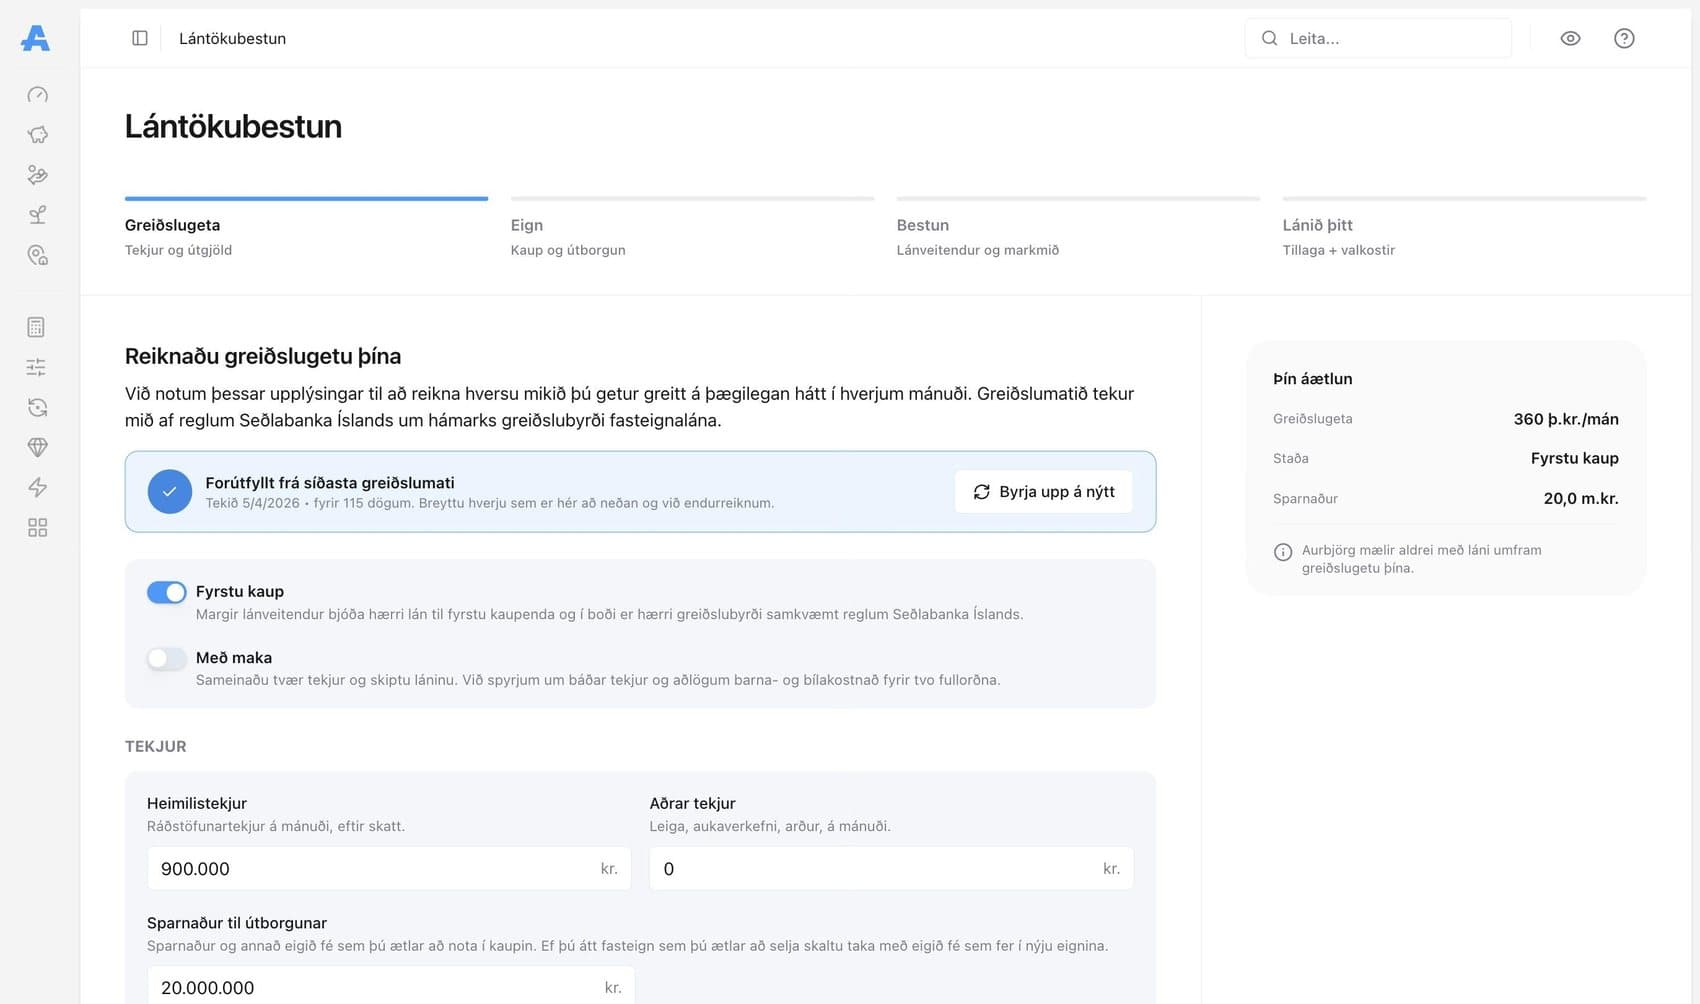
We calculate how much you can comfortably pay each month. The assessment follows the Central Bank of Iceland's rules on the maximum payment burden for mortgages.
You enter income, savings, other loans and expenses, and immediately see your payment capacity, purchasing capacity and borrowing capacity.
If a payment assessment has already been made with Aurbjörg, we prefill everything for you. You change what needs changing and we recalculate.
First-time buyers get more room
One setting in the first step lets you explore a first-time purchase. If you are eligible as a first-time buyer, the optimizer takes account of the applicable rules and available terms.
The share of disposable income, after tax, that may go towards loan payments under the Central Bank of Iceland's rules. In an example with 700,000 kr. a month, payment capacity goes from 245,000 kr. to 280,000 kr.
The share of the purchase price you need to put down, corresponding to 90 % loan-to-value instead of 80 %. On a property costing 70 m.kr. that is 7 m.kr. instead of 14 m.kr., a threshold 7 m.kr. lower.
With some lenders the highest loan-to-value tiers carry higher rates; with others the rates are the same as at 80 %. The optimizer compares every lender you selected and finds where a larger loan costs you least.
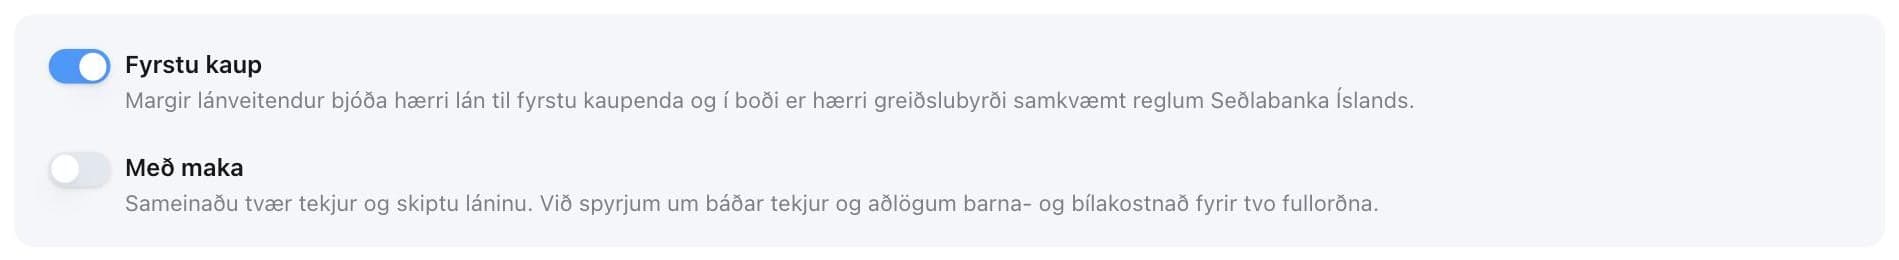
Is anyone in the household buying their first property? Switch on First purchase and we recalculate everything.
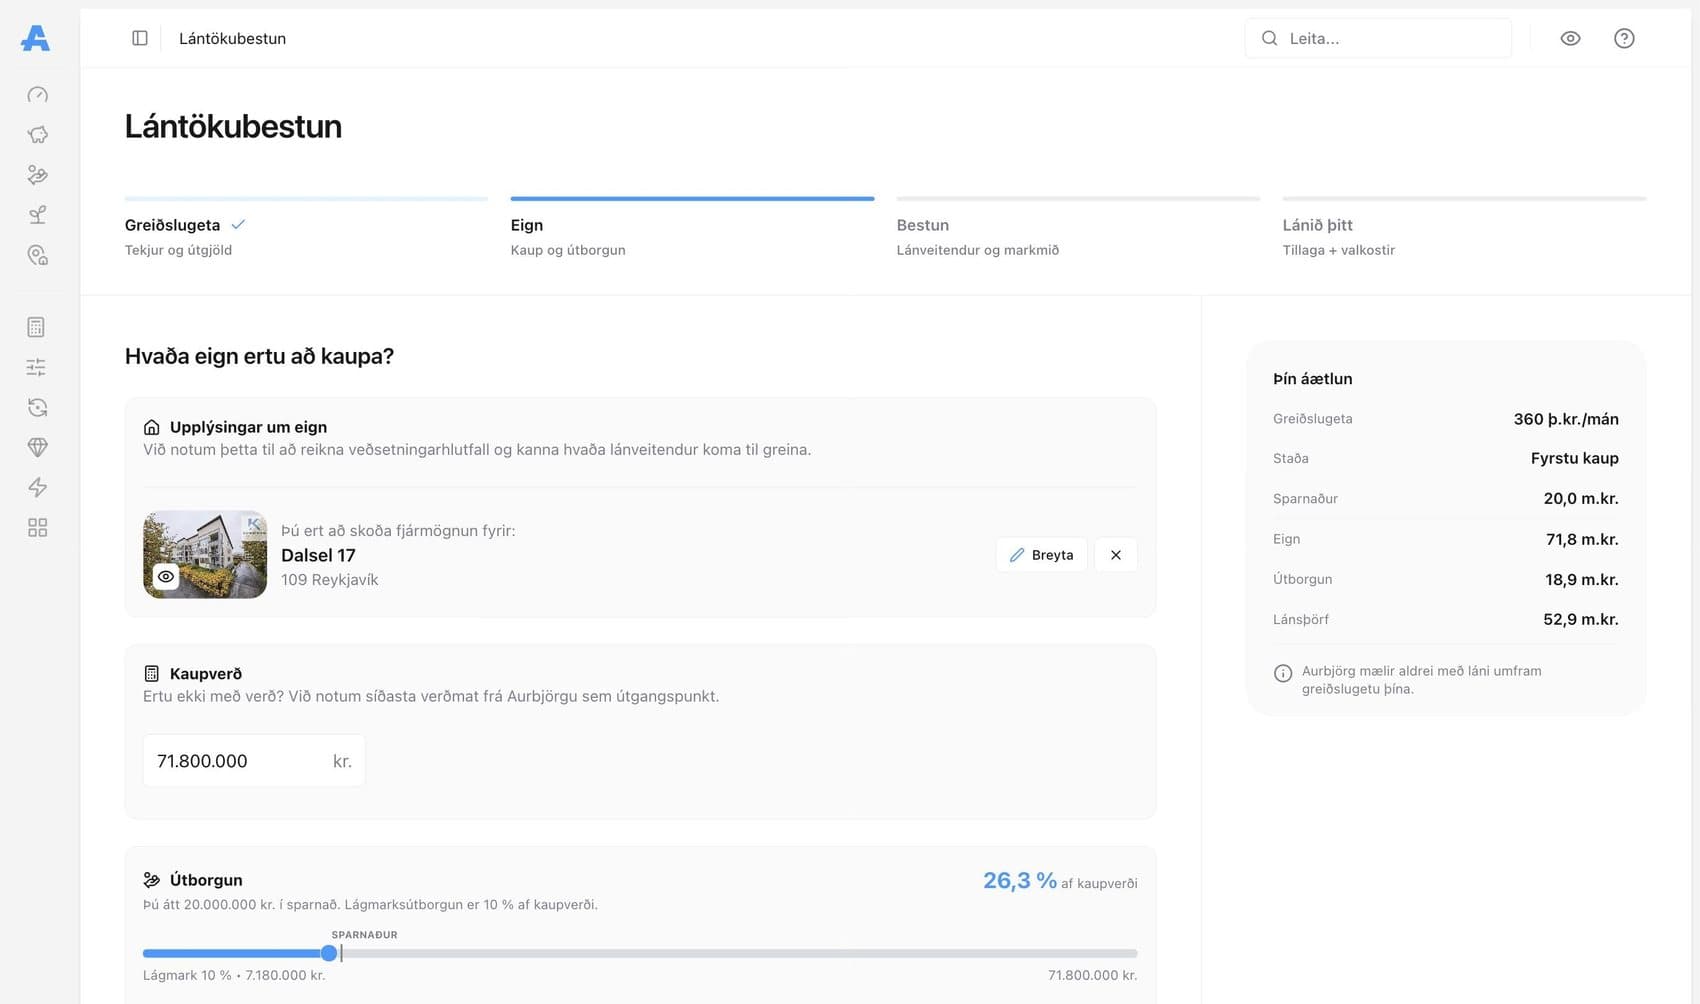
The property and the down payment
Choose the property you are buying. If you do not have a purchase price, we use Aurbjörg's most recent valuation as the starting point.
You set the down payment with a slider or enter an exact amount, and see the borrowing need and the loan-to-value ratio update as you go.
Borrowing based on your goals
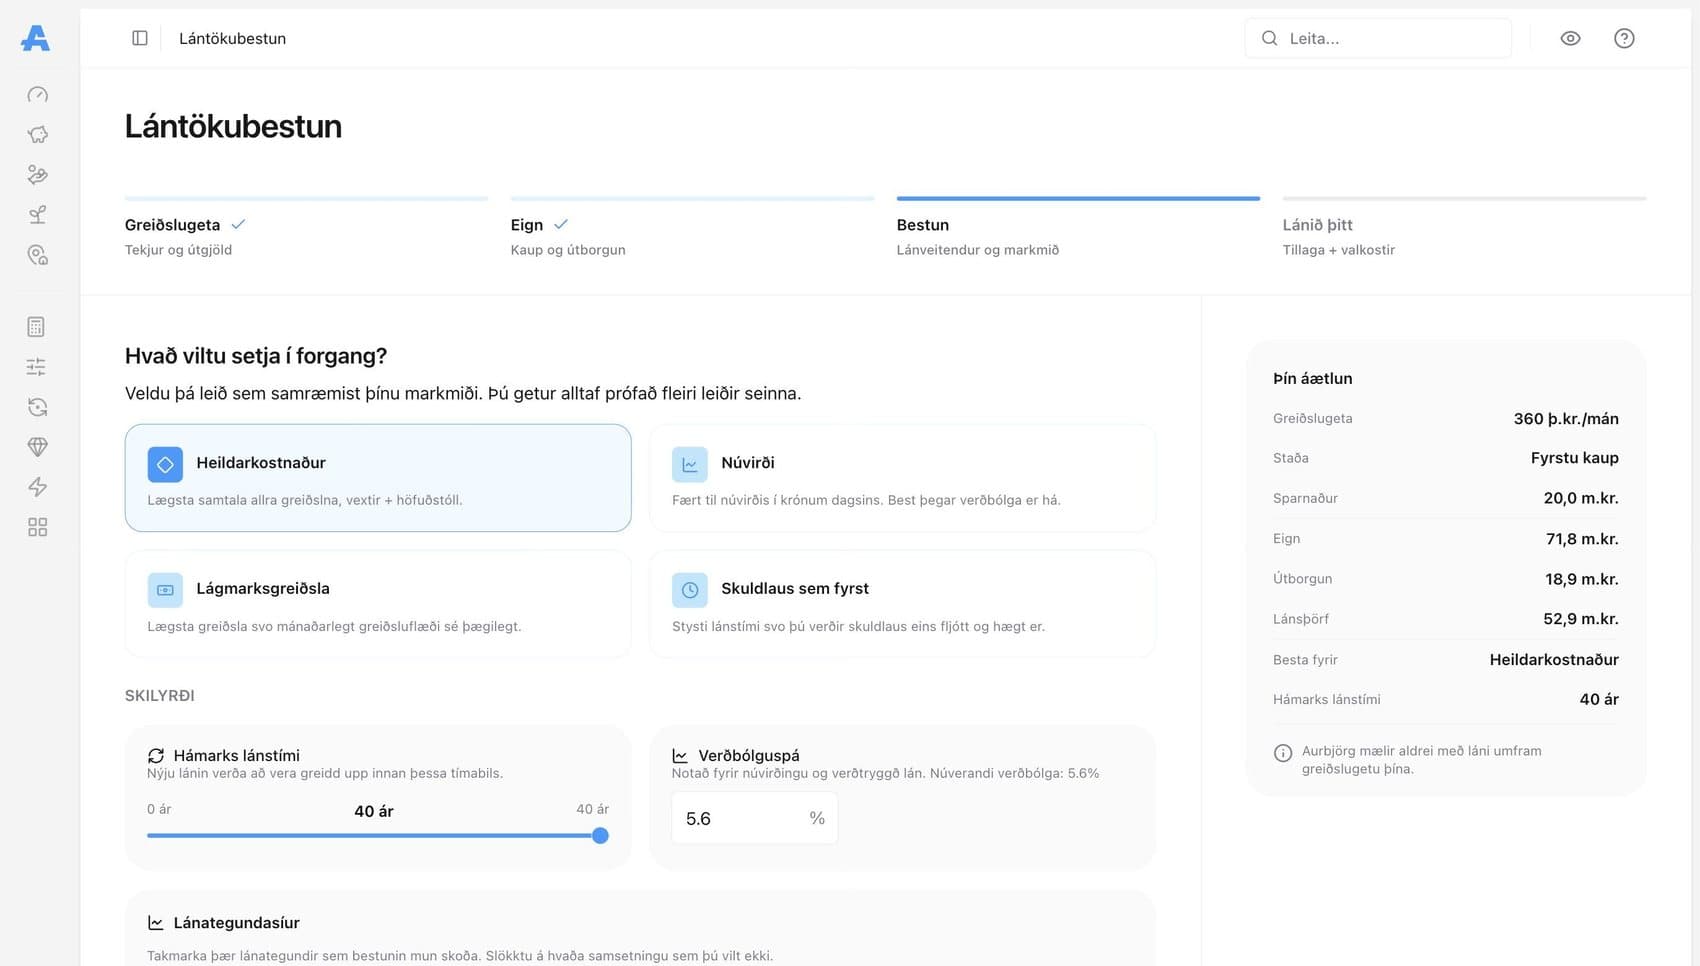
You choose what matters most to you and the optimizer ranks every route by that goal.
- The lowest total cost The lowest sum of all payments, interest and principal.
- The lowest present value The payments discounted to present value, in today's krónur.
- The lowest monthly payment The lowest payment, so the monthly burden is comfortable at the start.
- Becoming debt-free as soon as possible The shortest loan term, so you are debt-free as quickly as possible.
You can also set a maximum loan term and an inflation forecast. You can always try more routes later and compare them.
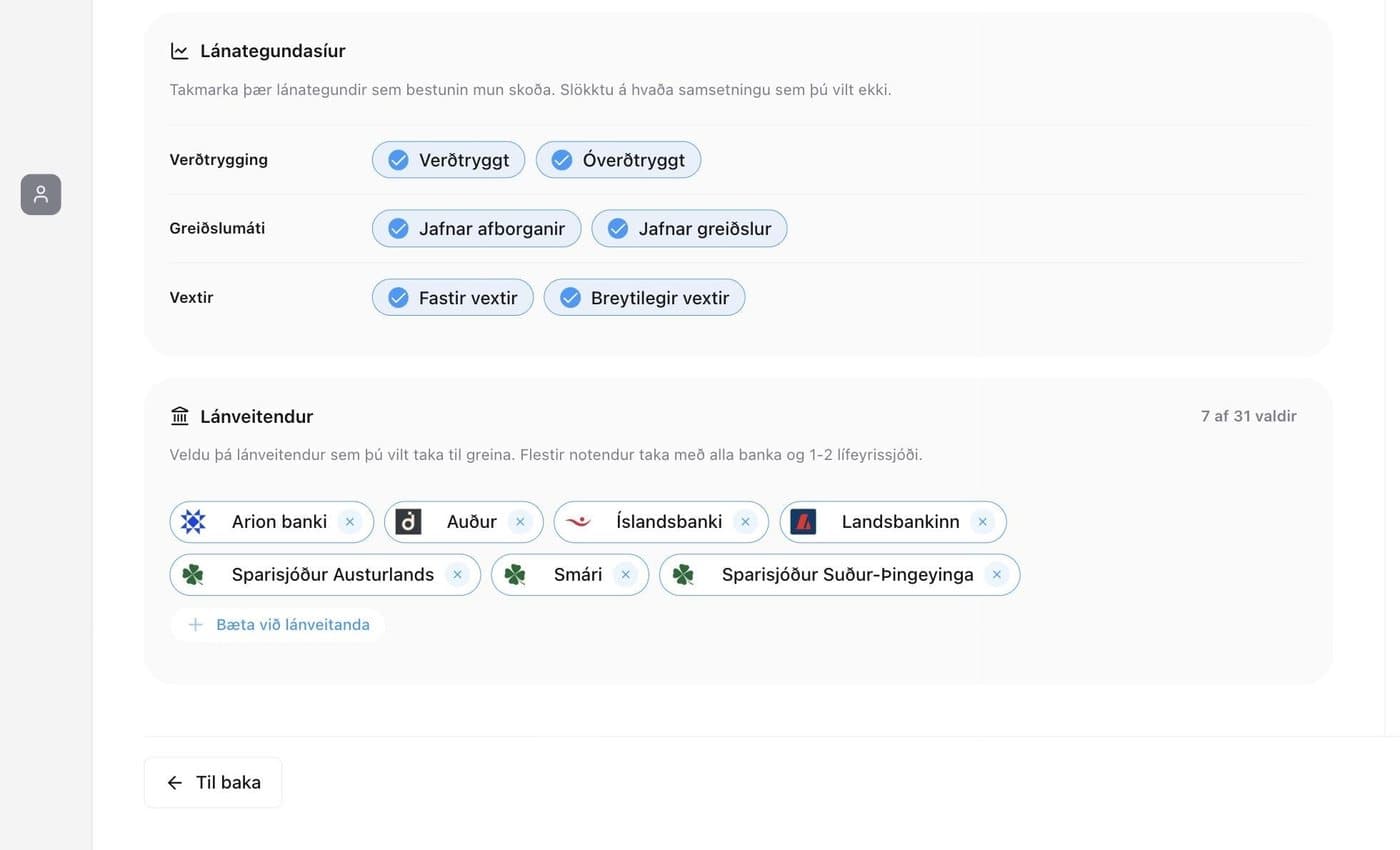
You choose the lenders and the loan types
Aurbjörg has the terms of 31 lenders on file: banks, savings banks and pension funds. You choose which of them the optimizer should take into account. Most people include all the banks and one or two pension funds.
You can also limit the loan types the optimizer considers. Indexed or non-indexed, equal principal payments or equal payments, fixed or variable rates. Switch off any combination you do not want.
What results do you get?
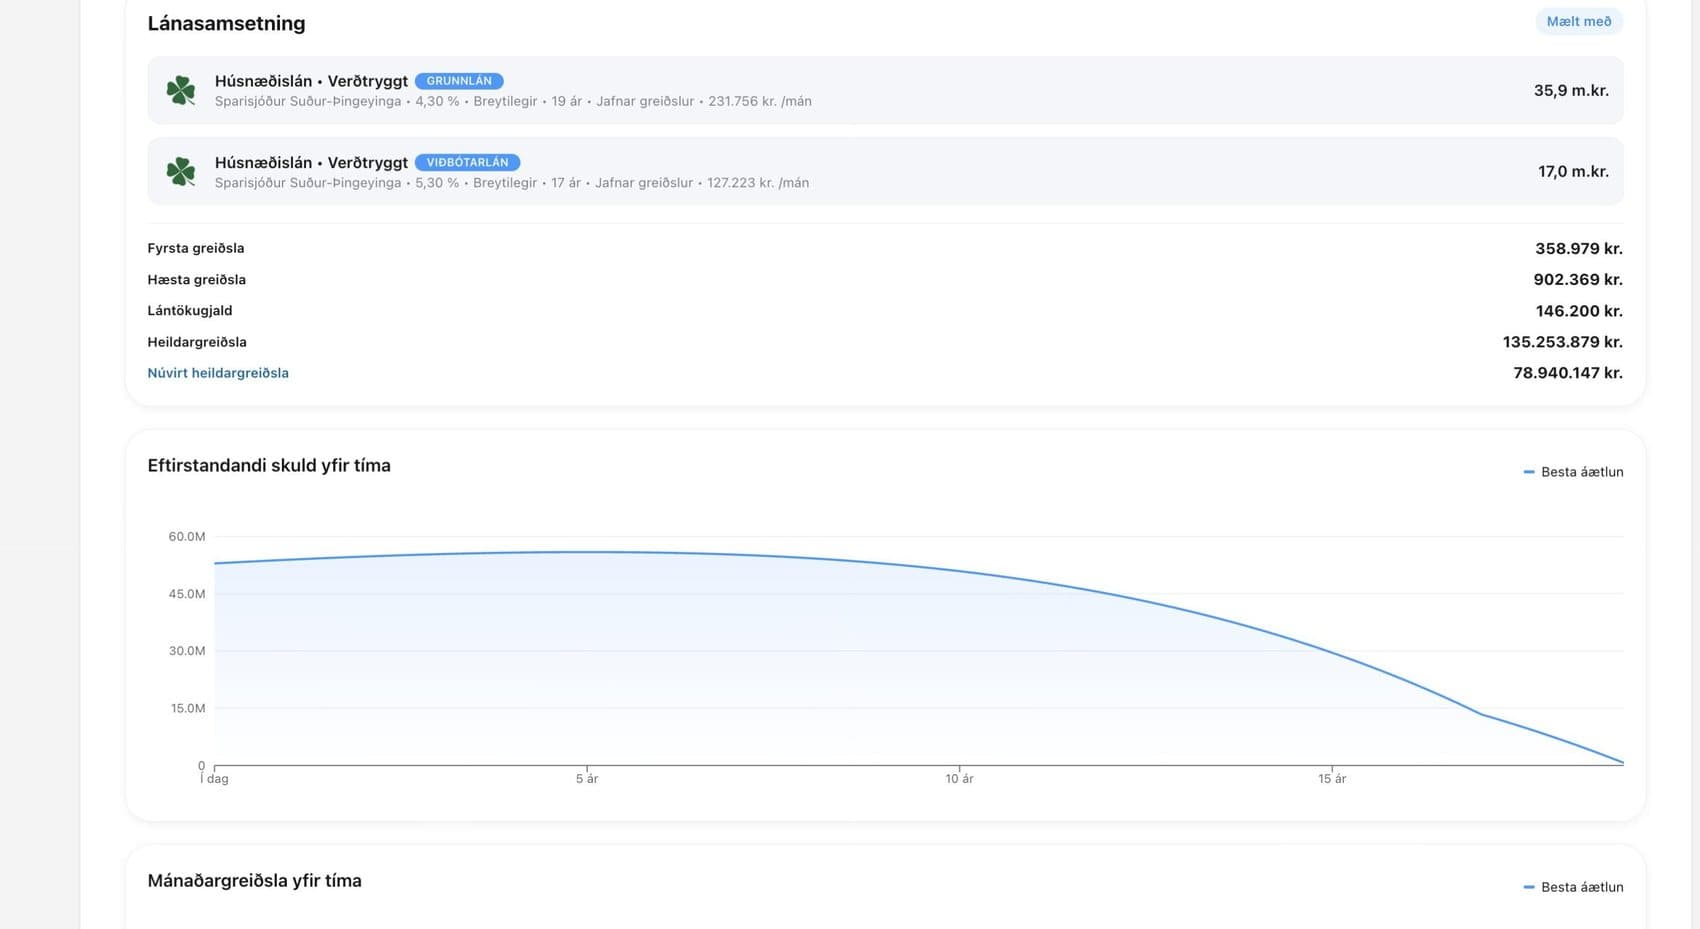
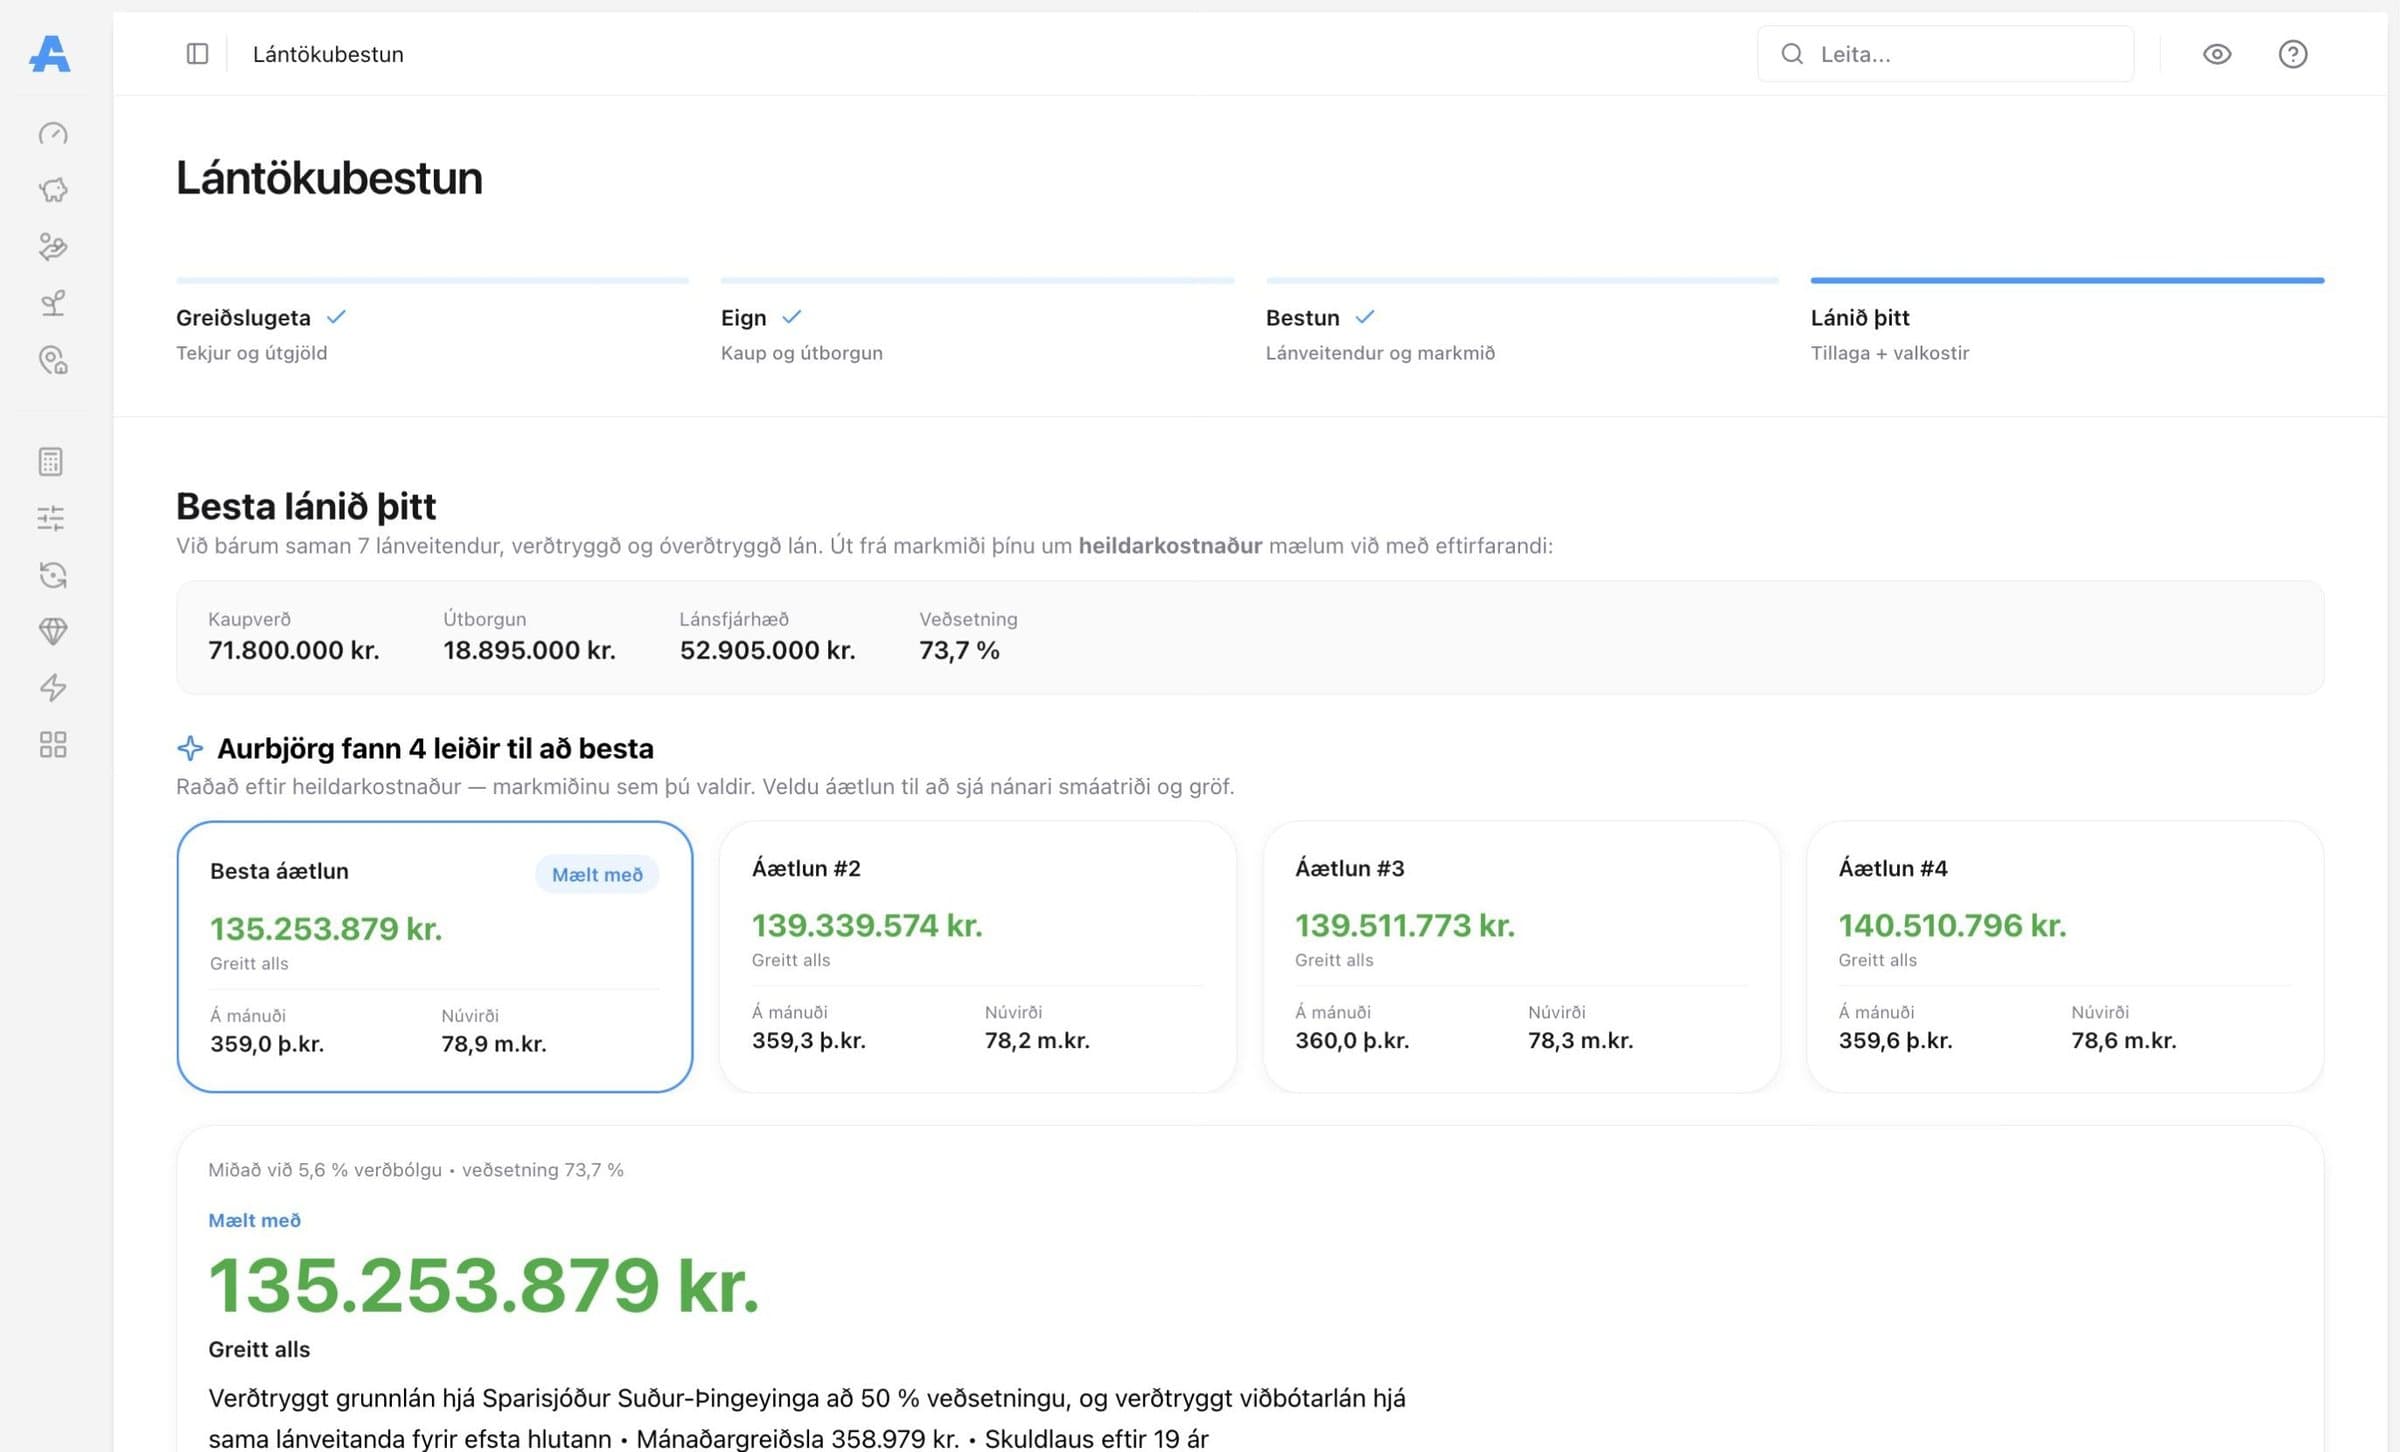
The Loan Optimizer shows you several different loan plans you can review and assess, ranked by the goal you chose.
You see exactly which loans make up each plan, with which lender, on what terms, at what loan-to-value ratio and of what type.
You see the total payment and the present-value total payment, the first and the highest monthly payment, the origination fee and when you will be debt-free. The charts show the outstanding debt and the monthly payment across the whole loan term.